Bridging finance
Get Your
Bridging Loan Quote
in Minutes
Need a Bridge Loan? Get Up to 90% of the Purchase Price with Low Friction Bridging Finance
- Terms in 5 minutes
- Completion in 5–20 days
- Dedicated bridging specialist
- Dual legal representation
Three steps between you and funding.
Fill in a 3-minute questionnaire
Receive your indicative terms
Complete and receive your funds
Deals we've funded
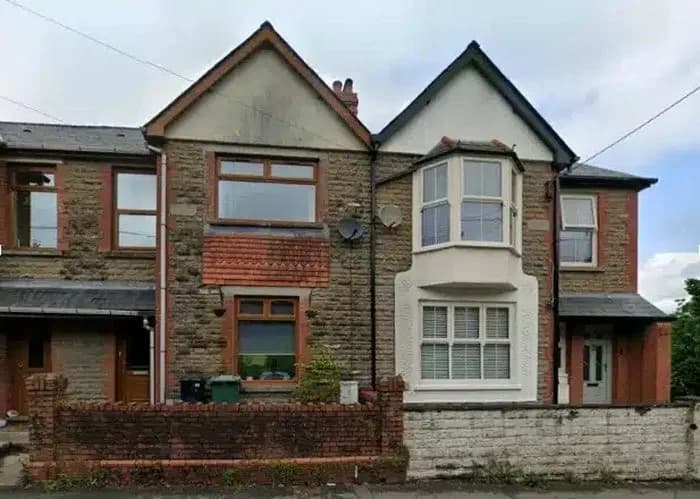
Auction purchase
Completed Feb 2026Wales
- Gross loan
- £85,000
- LTV (purchase)
- 88%
- Valuation
- £130k
- LTV (value)
- 57.7%
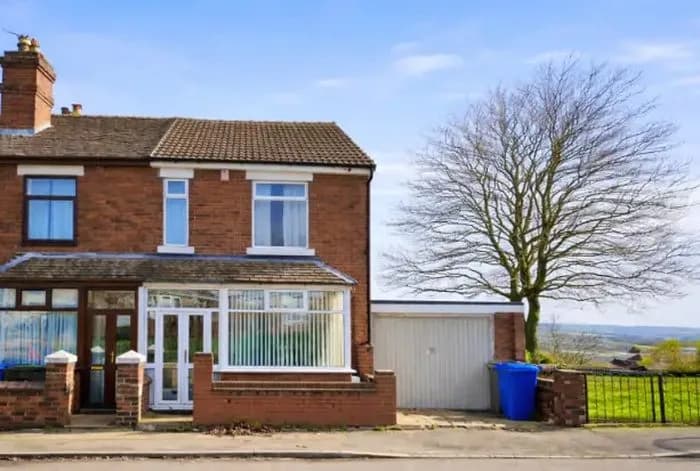
Auction purchase
Completed March 2026West Midlands
- Gross loan
- £67,500
- LTV (surveyor)
- 75%
- Purchase price
- £110k
- Surveyor value
- £90k
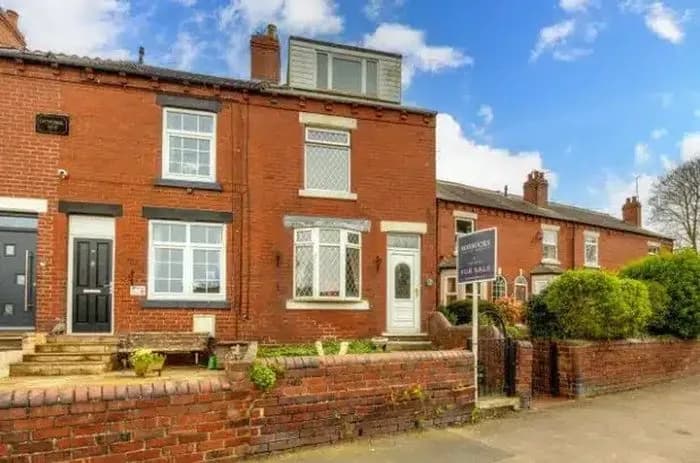
Refurbishment
Completed April 2026Yorkshire
- Total facility
- £94,000
- LTV
- 75%
- Main advance
- £69k
- Refurb advance
- £25k
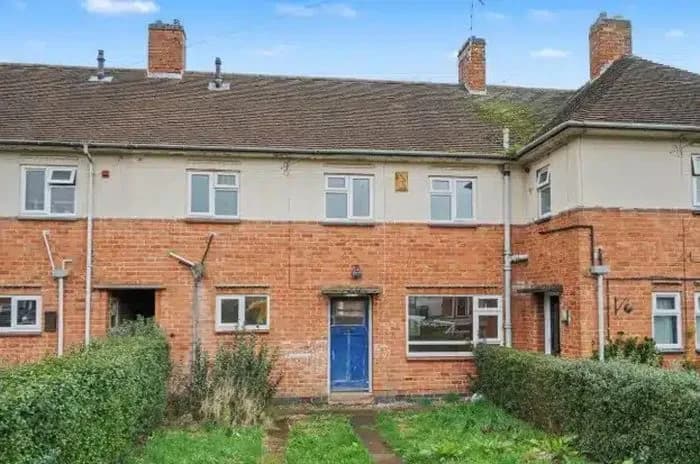
Refurbishment
Completed May 2026Leicestershire
- Gross loan
- £92,000
- LTV
- 65.25%
- Purchase price
- £141k
- Refurb budget
- £35k
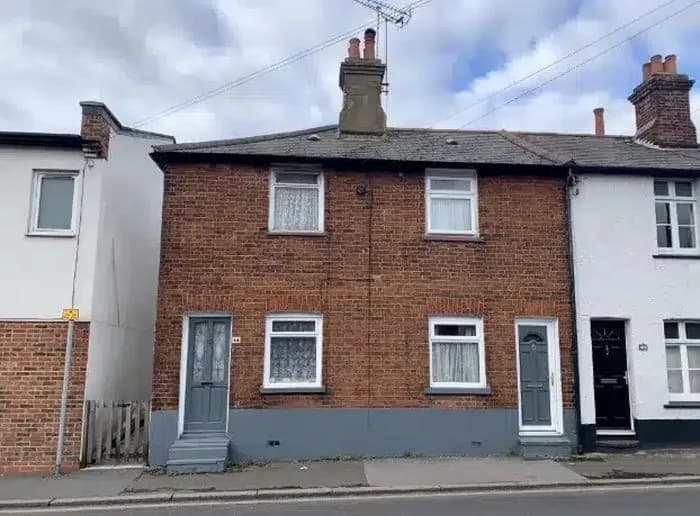
Heavy refurbishment
Completed March 2026Essex
- Gross loan
- £163,500
- LTV
- 75%
- Future GDV
- £450k
- Refurb advance
- £100k
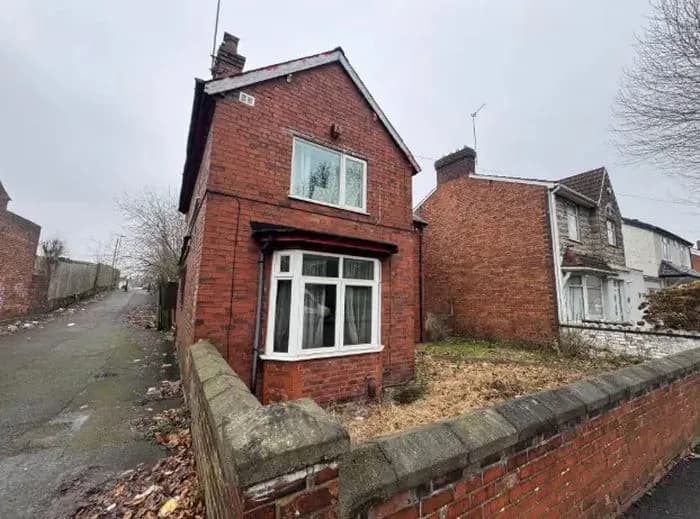
HMO conversion
Completed May 2026West Midlands
- Gross loan
- £162,000
- LTV
- 70%
- Rooms to let
- 5 beds
- Exit strategy
- Refinance
As featured in

Bridging loan questions, answered
How quickly can a bridging loan complete?
Most of the facilities we arrange complete in 5 to 20 days from application. Speed depends mainly on how fast the valuation can be booked and how quickly your solicitor returns the legal pack, which is why we offer dual legal representation to keep both sides moving on one timeline.
How much can I borrow, and at what LTV?
Facilities run from £30,000 to £2 million, at up to 90% loan to value. The maximum you can borrow depends on the property, your exit strategy and the lender's view of the security, so the figure in your indicative terms may differ from the headline maximum.
What does a bridging loan cost?
Rates start from 0.75% per month and are quoted monthly rather than annually because a bridge is short-term finance. On top of the interest you should budget for an arrangement fee, a valuation fee and legal costs. Your indicative terms set out each of these separately so you can see the total cost of the facility before you commit.
Do I need to pay interest every month?
Not usually. Most bridging facilities let you roll up or retain the interest so nothing leaves your account during the term, and the interest is settled when you repay. Serviced monthly interest is also available if you would rather keep the redemption figure down.
What is an exit strategy and why does it matter?
Your exit is how you intend to repay the bridge — normally selling the property or refinancing onto a term mortgage. It is the single most important part of a bridging application, because the lender is underwriting the repayment route as much as the property itself. Having a credible, evidenced exit is what gets a case agreed quickly.
Can I get a bridging loan for an auction purchase?
Yes, and it is one of the most common reasons investors come to us. Auction contracts typically require completion within 28 days, which is faster than a standard mortgage can move. Apply before the auction and you will know your indicative terms and maximum loan before you bid.
Will applying affect my credit score?
No. Completing the questionnaire and receiving indicative terms involves no credit search. A credit check only happens later, with your consent, once you decide to proceed to a formal application.
Can I get a bridge with adverse credit?
Often, yes. Bridging lenders weigh the property and the exit strategy more heavily than credit history, so missed payments, defaults or a CCJ do not automatically rule you out. Tell us about it in the questionnaire and we will match you to the best offer for your circumstances.